
At a glance
- Investors have long used low interest rates in Japan as a source of funding overseas.
- Higher yen borrowing costs or abrupt moves in its exchange rate risks global instability across financial markets.
- Co-ordinated action by Japan’s central bank and the US Treasury have sought to reduce these risks.
Japan, one of the world’s largest economies, is struggling with a falling currency. The yen has been weakening against the US dollar, reaching its lowest level in almost 40 years. It’s also fallen against other currencies, including the pound. While that may sound like a problem confined to the other side of the world, it has become significant enough for both Japan and the US to step in and try to stabilise the situation.
Global investors as well as central banks are paying attention. It is a case of “what happens in Japan may not stay in Japan…” A prolonged decline in the yen has the potential to affect global bond markets, as well as borrowing costs for mortgage rates in the UK.
Need for action – Japan’s yen has fallen to multi-decade lows
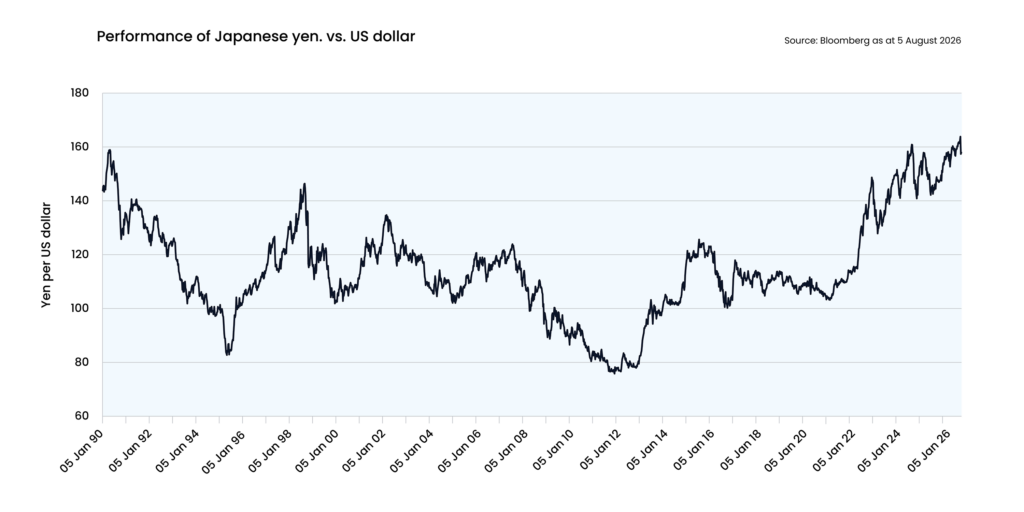
Why is the yen so weak?
For many years, Japan has faced slow economic growth, weak consumer spending and periods of falling prices. To provide support, the Bank of Japan has kept interest rates much lower than those in most other developed countries. Interest rates in the country were kept at, or below, 0% for almost 25 years until 2024. Even now, Japanese interest rates are around 1%, compared with 3.5%-3.75% in the US and UK. Yet unsurprisingly, investors will seek out the highest return they can get.
The yen carry trade
A key reason the weak yen matters is something known as the “yen carry trade”. In simple terms, investors borrow money cheaply in Japan and invest it in assets that offer higher returns abroad. Those assets might include government bonds, company shares, property or commodities. As a result, many Japanese-based investors have moved money into assets that offer better yields elsewhere, particularly in the United States. This persistent selling has pushed the value of the yen lower.
While Japanese interest rates remain low, the strategy can be highly profitable. Yet, if Japanese interest rates rise, or there is an abrupt move in the yen exchange rate, the yen carry trade becomes riskier.
It will often result in selling overseas investments and buying yen to pay back their loans. What was once a steady flow of money out of Japan can quickly reverse.
Why bond markets are watching closely
Japanese investors are among the biggest foreign owners of US government bonds, known as Treasuries. If they begin selling these bonds in significant quantities to move money back to Japan, Treasury prices could fall (and yields, which move in the opposite direction, rise).
Bond yields have a direct influence on borrowing costs throughout the economy. Governments, companies and households all pay close attention to them. When bond yields rise, borrowing generally becomes more expensive.
In the US, long-dated Treasury yields are at a 19-year high. Investor concerns about debt sustainability, inflation and the consequent need for additional compensation are pushing these yields even higher. Any selling by Japanese holders would likely push US Treasury prices lower (and yields higher). A 0.25% rise in interest rates adds between $80 billion – $100 billion to the federal government’s interest bill.
What does this mean for mortgage holders?
Mortgage rates are heavily influenced by movements in bond markets. Higher government bond yields tend to push up the cost of lending across the financial system.
That means moves in the Japanese yen could eventually be felt by homeowners, businesses and borrowers thousands of miles away in the US, UK and across Europe. A large-scale unwinding of the yen carry trade could put upward pressure on bond yields and make borrowing more expensive more broadly.
This is one reason the US has been keen to support efforts to stabilise the yen. The US is already dealing with elevated borrowing costs and does not want additional pressure pushing Treasury yields even higher.
Summary
The recent intervention to support the yen highlights how interconnected global financial markets have become. A currency problem that begins in Japan can quickly spill over into bond markets, affecting borrowing costs around the world. Stress in one corner of the financial system can eventually affect everything from bond prices to mortgage rates closer to home.
SJP Approved 13/08/2026
Join us on social
Edinburgh
Head Office
Verdant Building, 2 Redheughs Rigg,
Edinburgh ,
EH12 9DQ
T: 0131 510 8610
View The Edinburgh Office
Inverness
7 Connel Court, Ardconnel Street,
Inverness,
IV2 3EY
T: 01463 221 221
View The Inverness Office
Inverness
Third Floor, Suite 3A1, Metropolitan House, 31-33 High Street,
Inverness,
IV1 1HT
T: 01463 258058
View The Inverness Office
London
Number 33,
St. James's Square
London,
SW1Y 4JS
T: 0131 510 8610
View The London Office
Email us: [email protected]